TDS on Property Transactions: A Buyer and Seller Guide
28 Jun 2026 · 3 min read
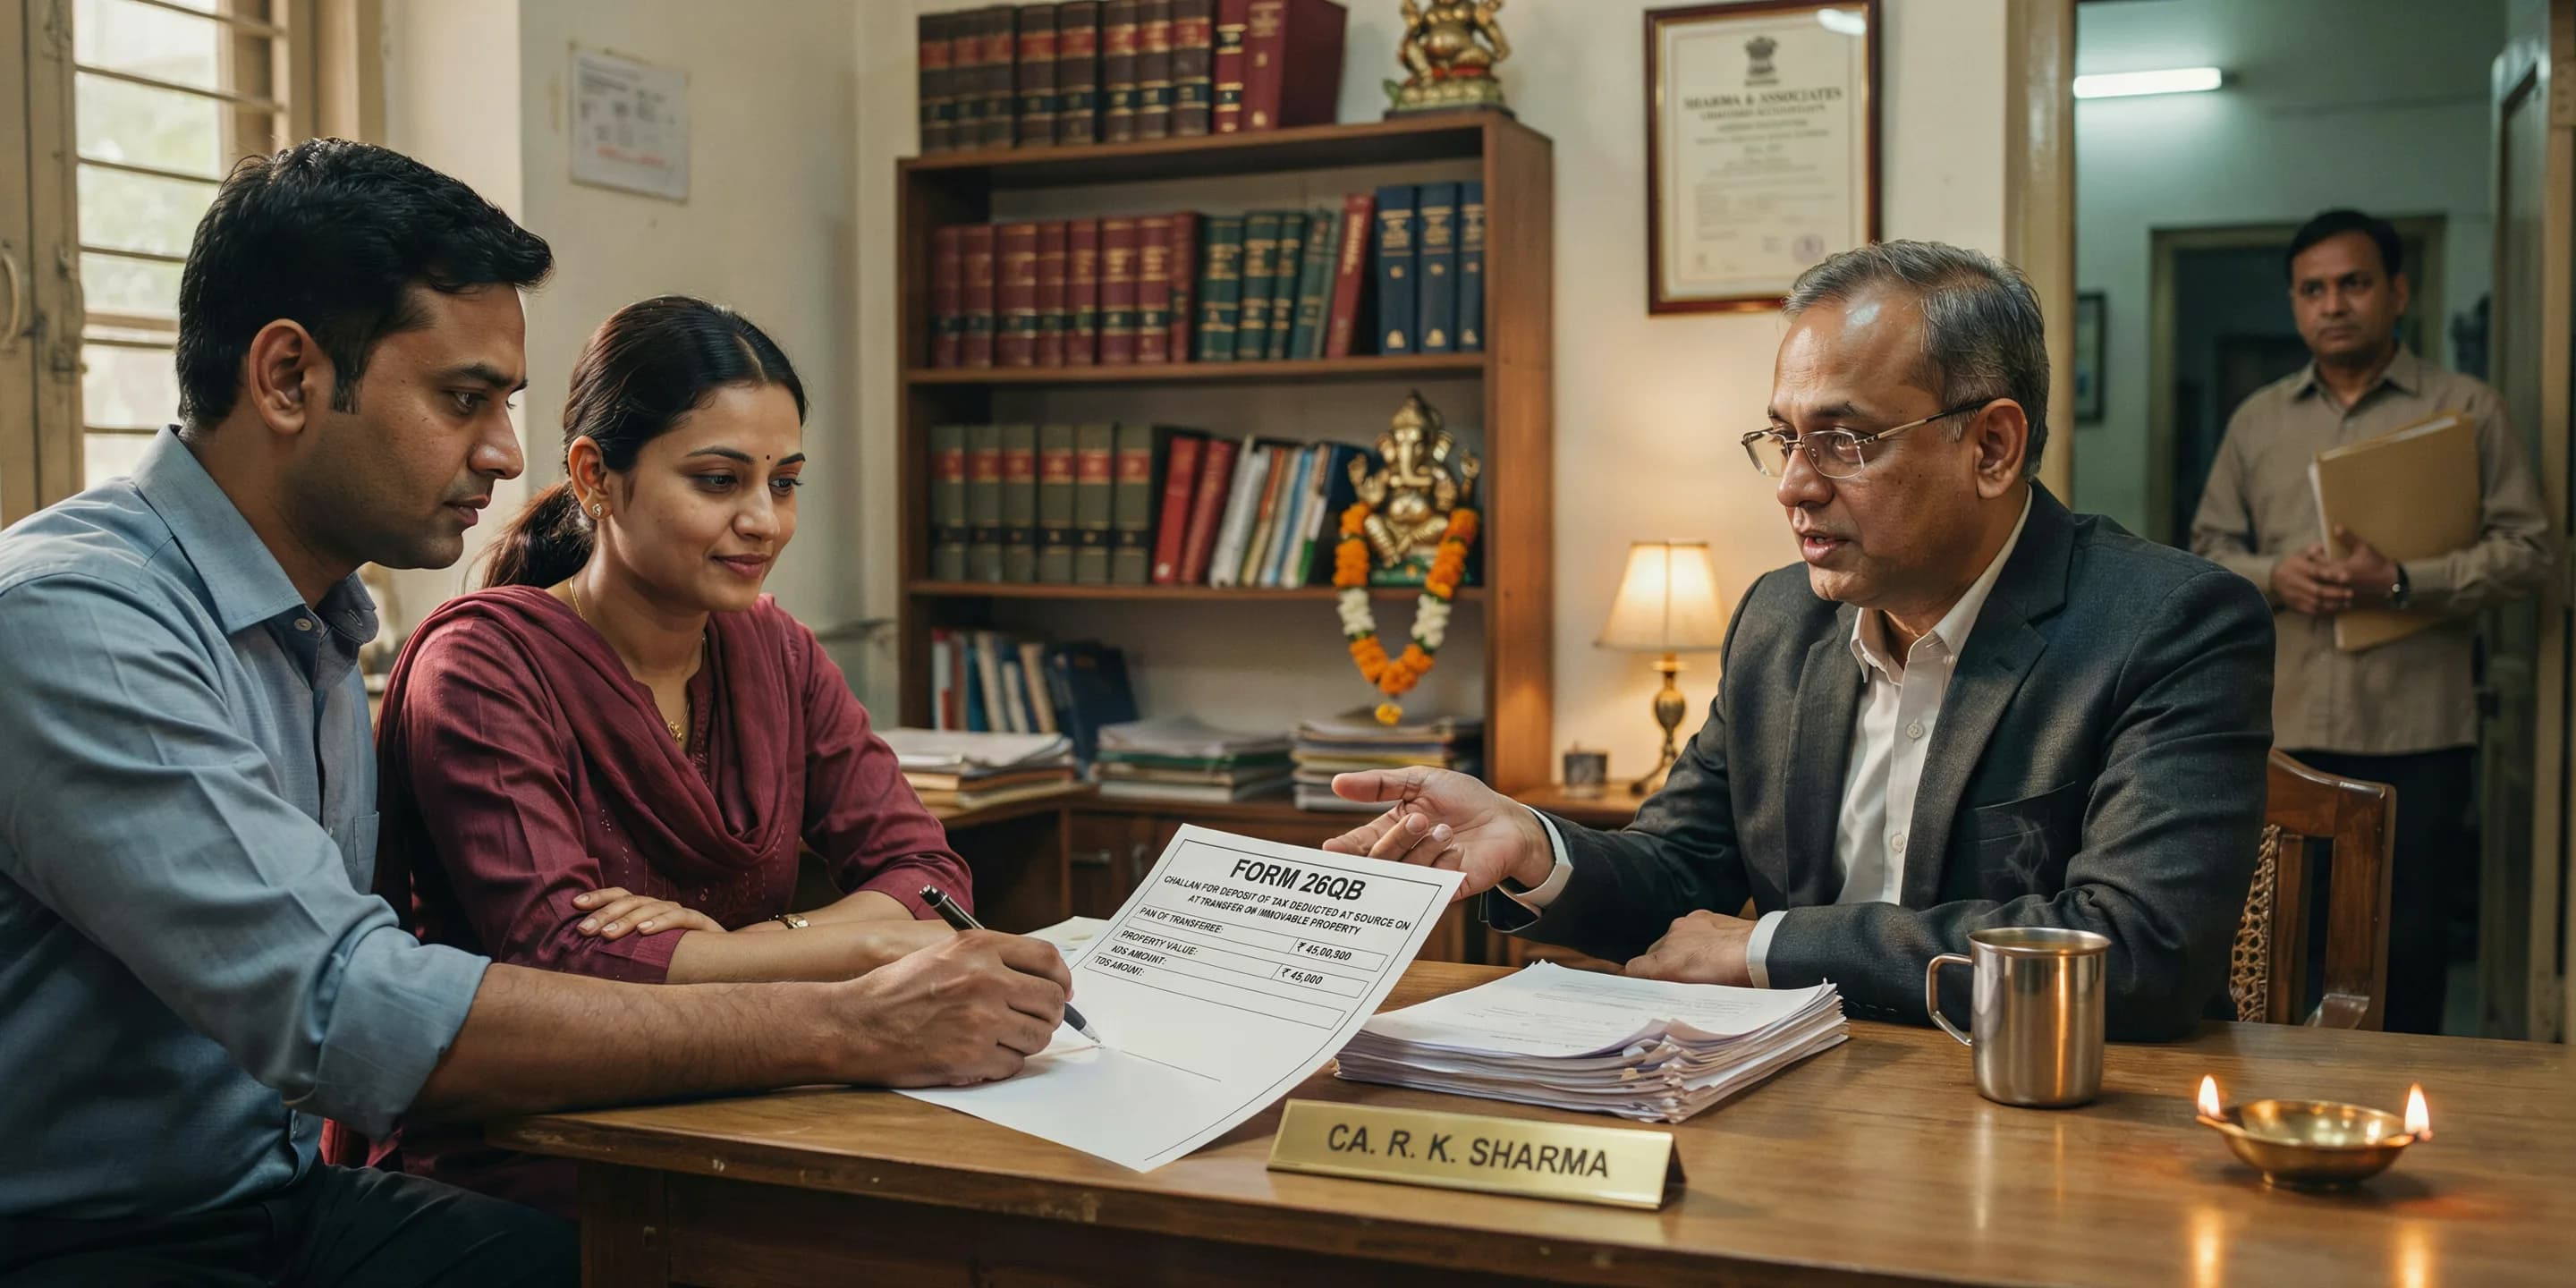
Section 194-IA requires buyers of immovable property valued at INR 50 lakh or more to deduct TDS at 1% of the sale consideration. This applies to all buyers, whether individuals or companies, and regardless of whether they have a TAN.
The TDS must be deducted at the time of payment or credit, whichever is earlier. Payment to the government must be made within 30 days using Form 26QB. The buyer does not need a TAN for this specific TDS.
For properties below the stamp duty value, TDS should be deducted on the higher of sale consideration or stamp duty value. In case of multiple buyers or sellers, each buyer must file a separate Form 26QB for their share.
Non-compliance results in interest at 1% per month for late deduction and 1.5% per month for late deposit. The buyer also loses the ability to claim cost of acquisition for capital gains purposes.
Key areas covered:
- Applicable on properties valued INR 50 lakh or above
- TDS rate: 1% of sale consideration
- No TAN required use Form 26QB
- Payment to government within 30 days
- Compare with stamp duty value for TDS base
- Interest: 1% (late deduction) or 1.5% (late deposit) per month