GST Reconciliation Common Errors and How to Avoid Them
16 Jul 2026 · 2 min read
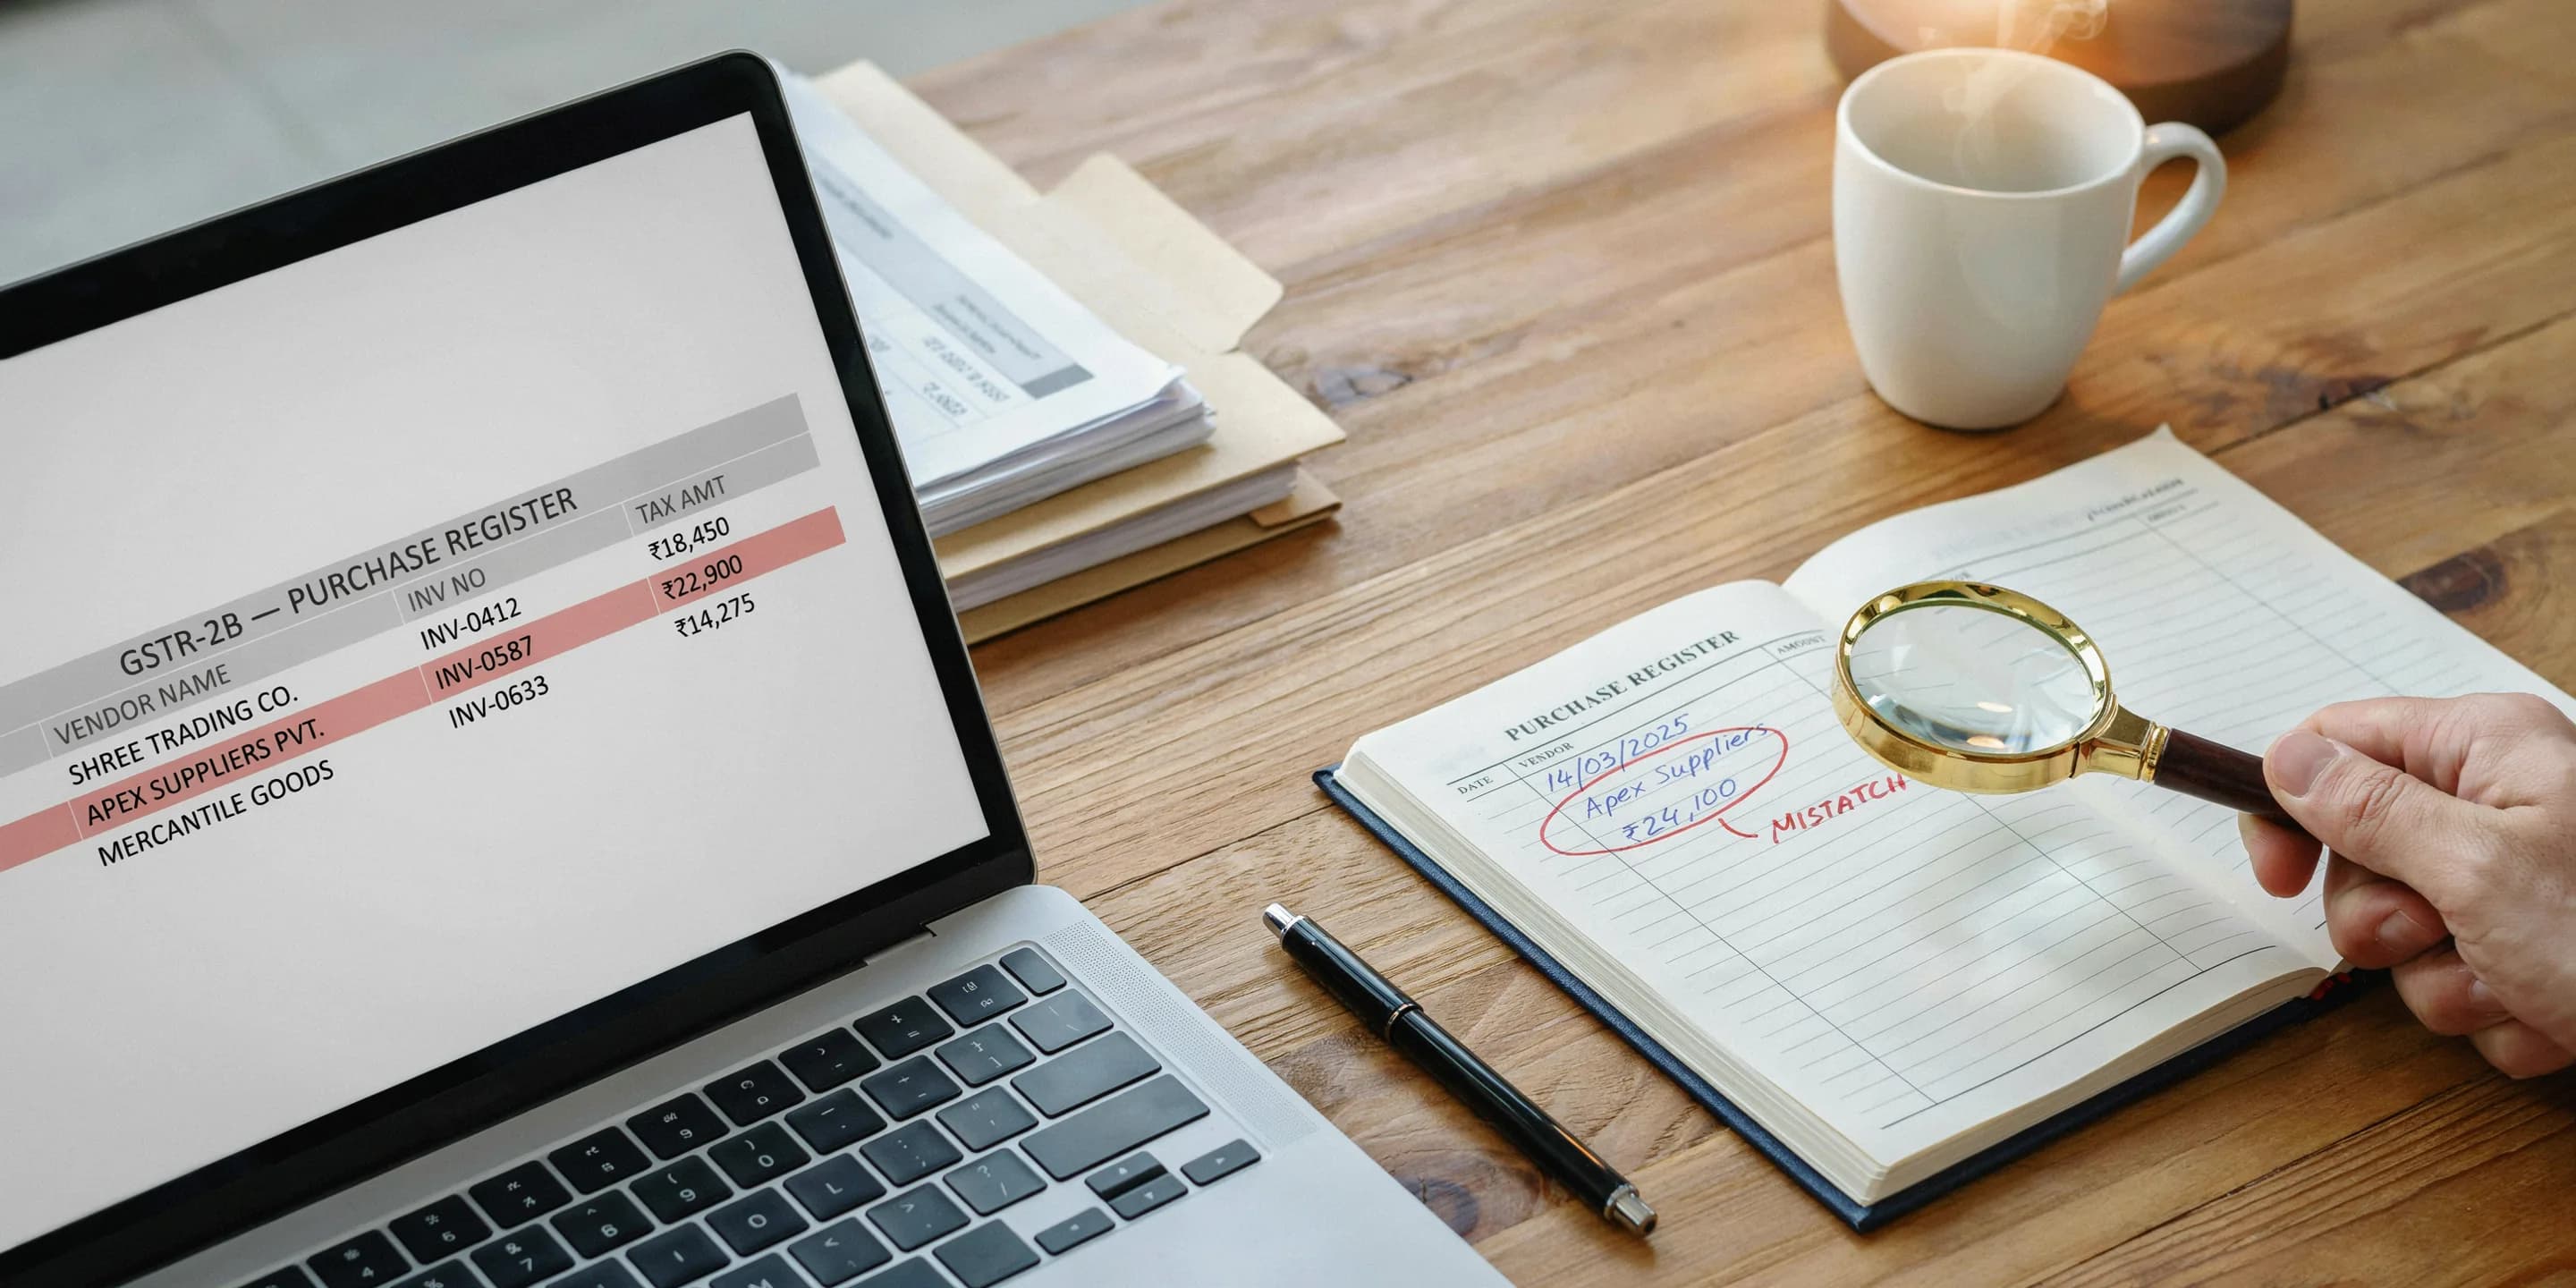
GST reconciliation remains one of the most challenging aspects of indirect tax compliance for businesses. Mismatches between GSTR-2B and books of accounts can lead to blocked ITC, notices, and unnecessary litigation.
The most common errors arise from timing differences between when invoices are uploaded by suppliers and when they reflect in the recipient's GSTR-2B. Businesses often claim ITC based on invoices received without verifying supplier compliance.
Another frequent issue is incorrect classification of supplies particularly around whether a transaction qualifies as a supply of goods or services, the applicable HSN/SAC codes, and the correct tax rate.
Regular monthly reconciliation between purchase register, GSTR-2B, and ITC claimed in GSTR-3B is essential. This should be done before filing returns, not after receiving a notice from the department.
Key areas covered:
- Match purchase register with GSTR-2B before claiming ITC
- Verify supplier filing status before claiming large ITC amounts
- Correct HSN/SAC classification to avoid rate disputes
- Maintain proper documentation for reverse charge supplies
- Reconcile credit notes and debit notes monthly
- Track the 180-day payment rule for ITC reversal