ESOP Structuring: A Practical Guide for Indian Startups
5 Jul 2026 · 4 min read
Employee Stock Option Plans (ESOPs) are a powerful tool for startups to attract and retain talent without immediate cash outflow. A well-structured ESOP aligns employee interests with company growth.
The typical ESOP pool ranges from 10-15% of fully diluted share capital. The pool size should account for current hiring needs plus 2-3 years of future grants. Board and shareholder approval is required under Section 62(1)(b).
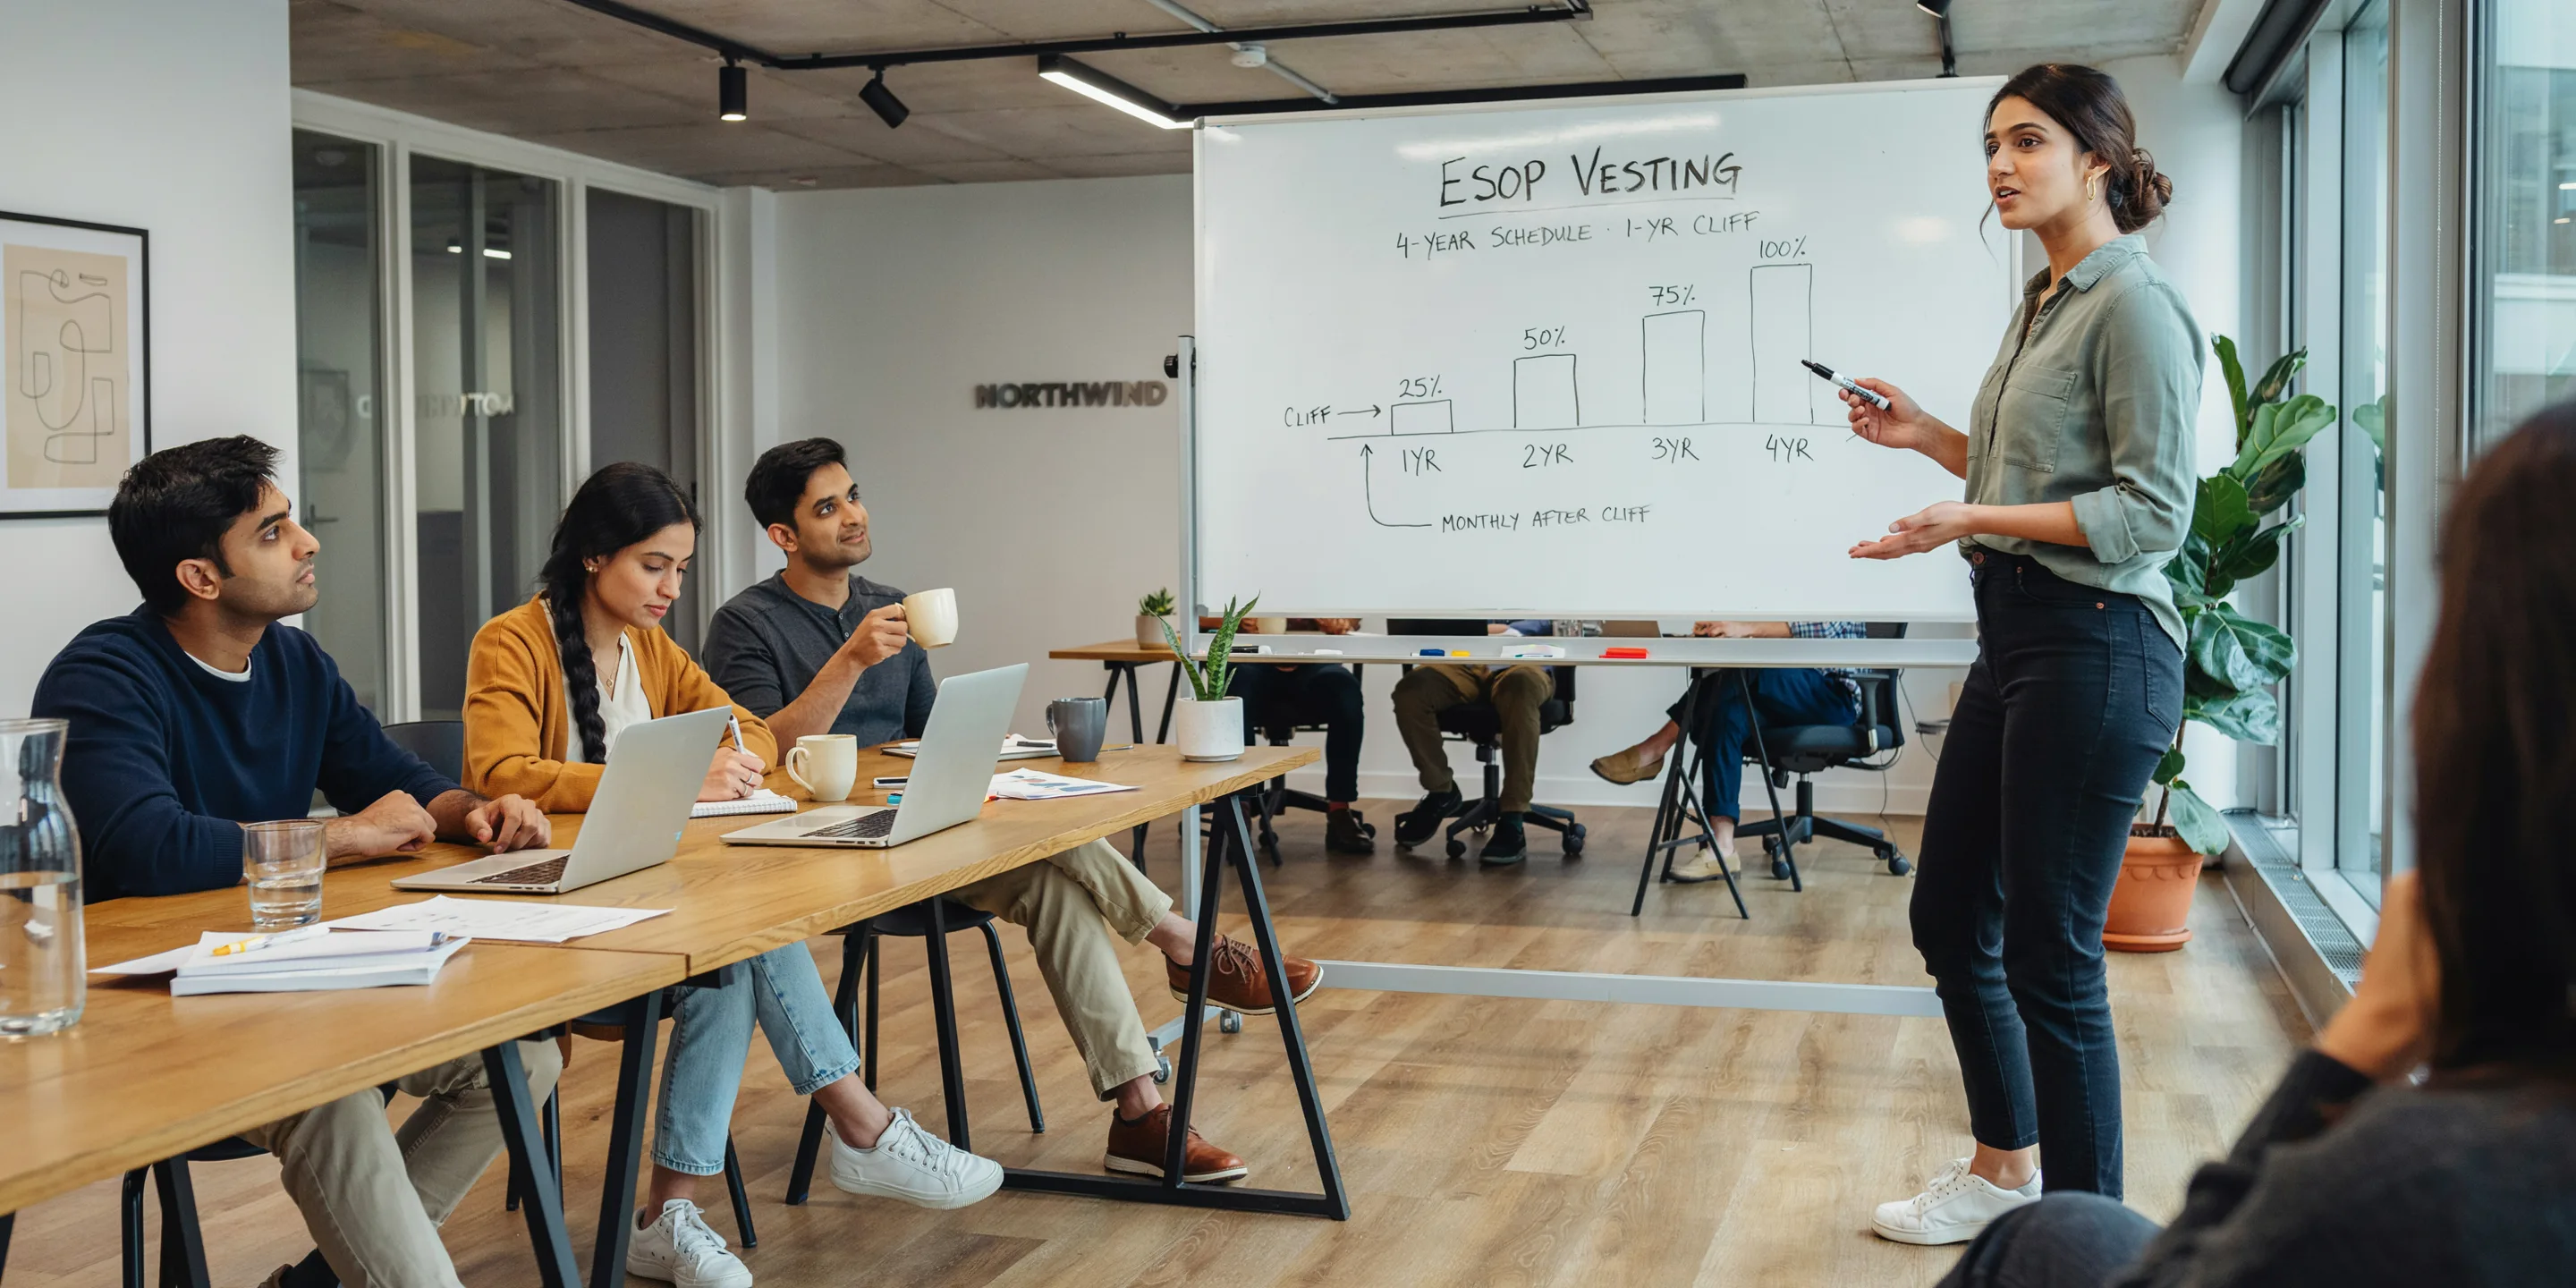
Key structuring decisions include vesting schedule (typically 4 years with 1-year cliff), exercise price (usually at fair market value or nominal value), and exercise window (period after vesting when options can be exercised).
Tax implications are two-fold: employees face tax at exercise (difference between FMV and exercise price as perquisite) and at sale (capital gains). Startups recognized under Section 80-IAC can defer the perquisite tax for up to 5 years from exercise.
Key areas covered:
- Typical pool size: 10-15% of fully diluted capital
- Standard vesting: 4 years with 1-year cliff
- Board + shareholder approval required under Section 62(1)(b)
- Tax at exercise: FMV minus exercise price as perquisite
- Section 80-IAC startups can defer perquisite tax 5 years
- Exercise window typically 5-10 years from grant date