Statutory Audit vs Tax Audit: What's the Difference?
26 Sep 2026 · 5 min read
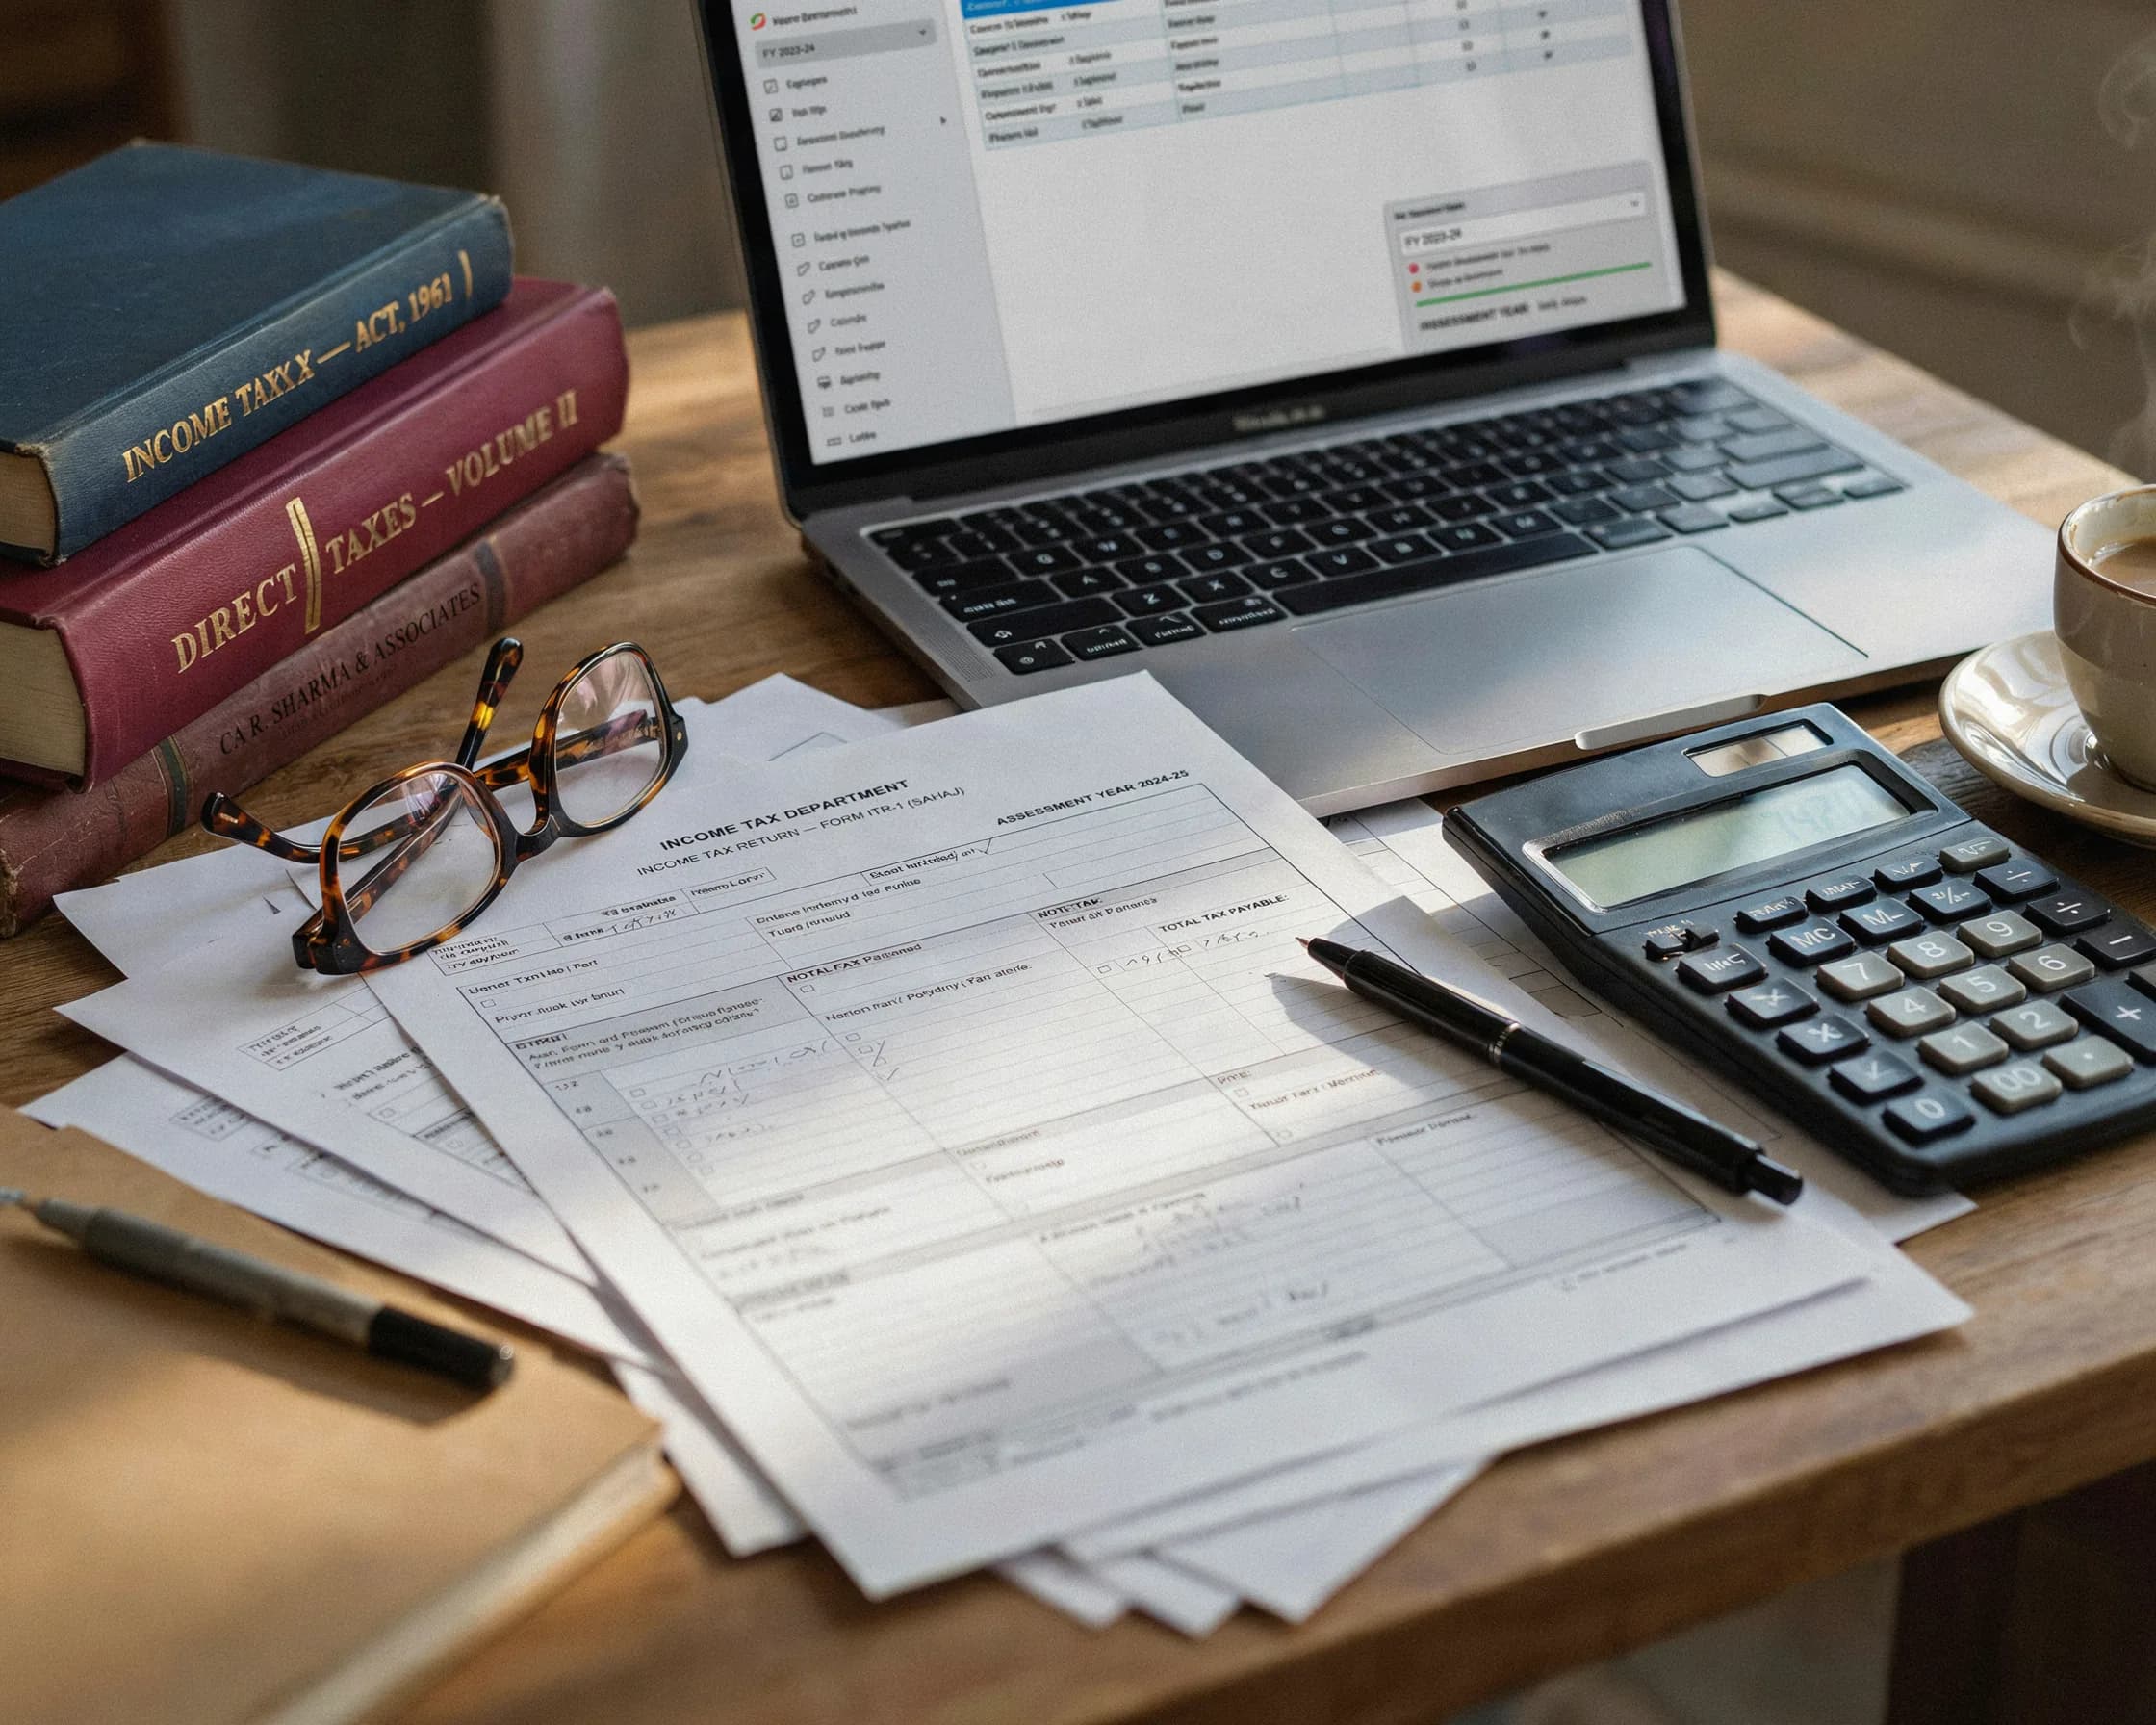
Tax audit in India and statutory audit are often confused with each other. But they are not the same.
They are required under different laws, have different purposes and can apply to the same business at the same time.
Understanding the difference helps business owners know what applies to them, prepare the right records and avoid last-minute compliance issues.
What Is a Statutory Audit in India?
A statutory audit in India is an audit that is required by the law governing a particular entity. For companies, the main law is the Companies Act, 2013.
Under Section 139, companies are generally required to appoint an auditor. Sections 139 to 147 cover areas such as auditor appointment, eligibility, duties and responsibilities.
The auditor reviews the company's financial statements and accounting records and provides an independent report based on applicable laws and auditing standards.
For a private limited company, statutory audit is generally required regardless of turnover or profit.
So, even a small or newly incorporated company will generally need to maintain proper books, prepare financial statements and get them audited.
What Is a Tax Audit in India?
Tax audit in India is required under income-tax law. Its purpose is different from a statutory audit.
A tax auditor reviews specific financial and tax-related information and reports the required particulars to the Income Tax Department. This helps ensure that taxable income and other relevant details are reported correctly.
Under the Income Tax Act, 2025, Section 63 corresponds to Section 44AB of the earlier Income-tax Act, 1961.
Tax audit can generally apply when:
These are tax audit thresholds, not thresholds for company statutory audits.
What Is the Main Difference?
The easiest way to understand it is:
In simple terms, statutory audit is mainly about financial reporting, while tax audit is mainly about tax compliance and reporting.
Can a Business Need Both?
Yes.
For example, suppose a private limited company has a turnover of Rs 60 lakh. It would generally need a statutory audit because it is a company. However, its turnover alone would not cross the general business threshold for tax audit in India, assuming no other tax-audit condition applies.
On the other hand, a business may cross the tax-audit threshold without being subject to a company-style statutory audit.
LLPs have their own rules. An LLP generally qualifies for an audit exemption if its turnover does not exceed Rs 40 lakh or its contribution does not exceed Rs 25 lakh, subject to the applicable rules. Tax-audit requirements must still be checked separately.
What Are the Tax Audit Forms and Deadlines?
For FY 2025-26 / AY 2026-27, tax-audit reports continue under the Income-tax Act, 1961. Depending on the circumstances, the applicable forms are 3CA-3CD or 3CB-3CD, with the tax-audit report due by 30 September 2026.
From Tax Year 2026-27, the Income-tax Act, 2025 applies and the new Form 26 consolidates the earlier tax-audit forms. The tax-audit report is due by 30 September 2027.
These changes relate to tax audit and do not remove statutory audit requirements under the Companies Act, 2013.
What Records Should Businesses Keep Ready?
Whether you need one audit or both, keeping your records organised throughout the year makes the process much easier.
Businesses should maintain:
Good accounting practices can save significant time when the audit begins.
Why Does Professional Audit Support Matter?
Professional audit and tax requirements depend on several factors, including your business structure, turnover, nature of activities and applicable laws.
Professional audit and tax advisory services can help identify which audits apply, prepare records, reconcile GST and TDS information and manage compliance timelines.
For companies, professional support can also help coordinate the statutory audit, financial statements and related ROC compliance.
Final Takeaway
Statutory audit and tax audit are not the same.
A statutory audit generally arises from the law governing the entity, while tax audit in India arises when specific income-tax conditions are met.
A business may need one, both or neither, depending on its structure and circumstances.
The best approach is to identify your audit requirements early, keep your records updated throughout the year and seek professional tax audit advisory service whenever the position is unclear.
Know which audit applies. Keep your records ready. Stay compliant.
Frequently Asked Questions
Is statutory audit in India mandatory for every private limited company?
Generally, yes. A private limited company is ordinarily subject to statutory audit irrespective of turnover.
Can a business have both statutory and tax audits in India?
Yes. They arise under different laws and can apply to the same business.
Does tax audit depend only on turnover?
No. Turnover is an important trigger, but certain presumptive-taxation conditions and other provisions can also create a tax-audit requirement.
Has tax audit law changed in 2026?
The Income Tax Act, 2025 applies from 1 April 2026. The tax audit framework has moved to the new Form 26 for Tax Year 2026-27.
Key areas covered:
- Statutory audit and tax audit are required under different laws and serve different purposes
- A private limited company generally needs a statutory audit regardless of turnover
- Tax audit applies when turnover exceeds Rs 1 crore (or Rs 10 crore with low cash transactions) or professional receipts exceed Rs 50 lakh
- A business can be required to have both audits at the same time
- LLPs have their own audit exemption thresholds separate from tax audit rules
- From Tax Year 2026-27 the new Form 26 under the Income Tax Act 2025 replaces the earlier tax audit forms