Tax Compliance for Real Estate Developers: Key Areas to Review
6 Nov 2026 · 6 min read
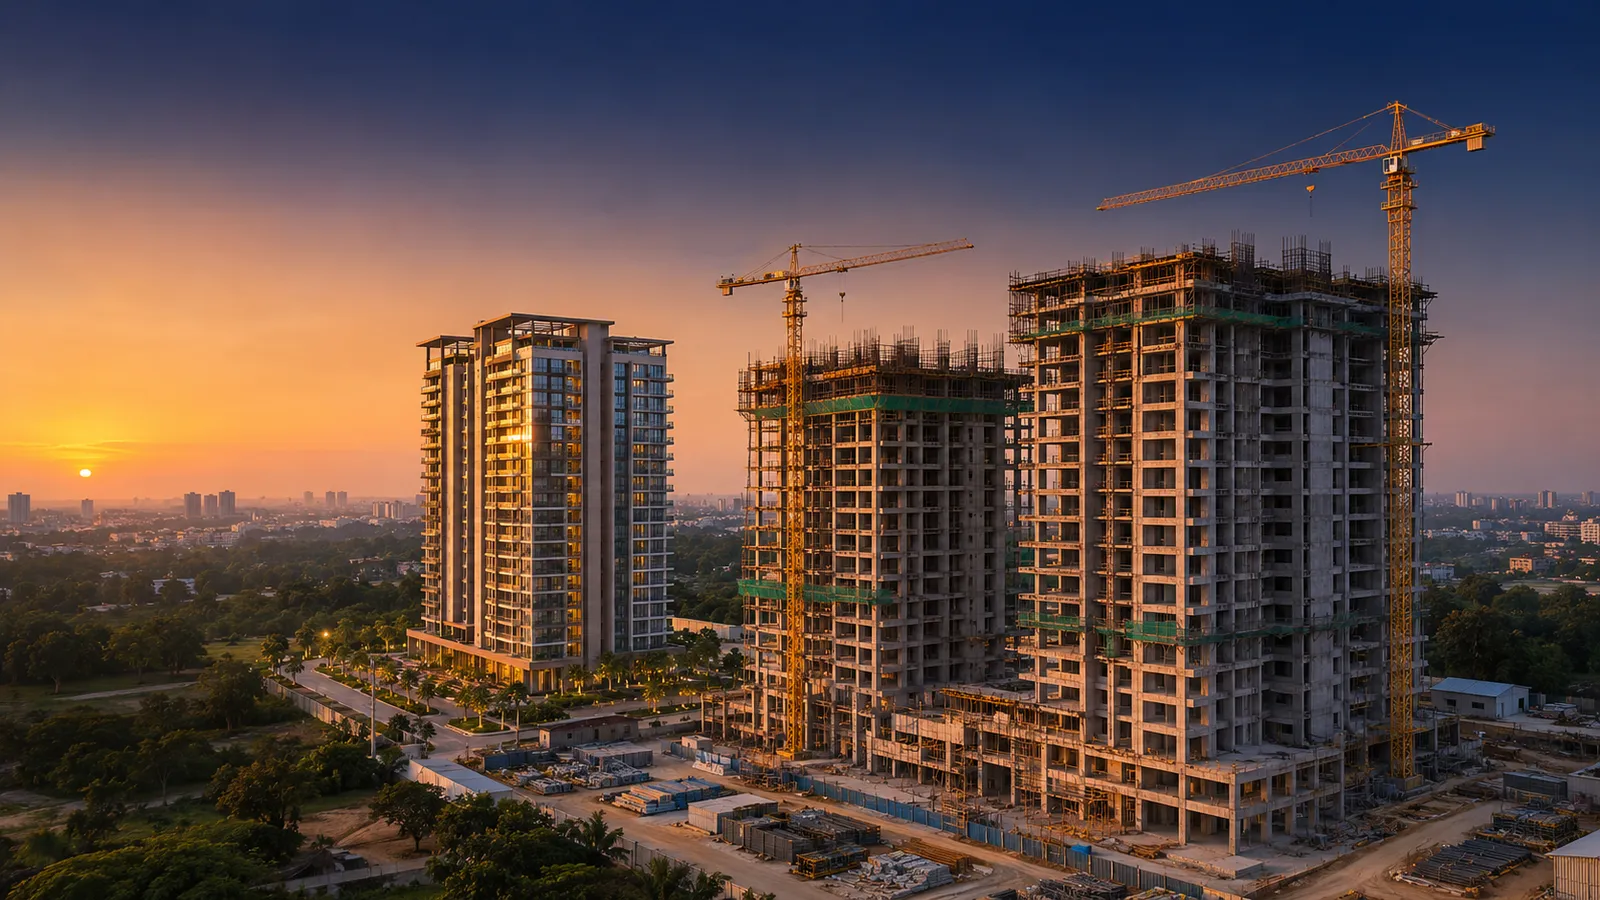
For real estate developers, real estate tax advisory services go far beyond calculating income tax. A single project can involve GST, income tax, TDS, stamp duty, RERA-linked documentation, joint development arrangements, landowner settlements, project finance and complex accounting. The right tax structure therefore needs to be considered from land acquisition through construction, sales, completion and final profit recognition.
Why Do Real Estate Developers Need Tax Advisory?
Real estate transactions are high-value, long-term and documentation-heavy. A tax position taken when acquiring land can affect the project's cost, GST treatment, cash flow and eventual profitability.
Professional real estate tax advisory services help developers evaluate:
The objective is not aggressive tax reduction. It is to structure transactions efficiently while remaining commercially practical and legally compliant.
How Does GST Apply to Real Estate Projects?
GST treatment depends significantly on the nature and stage of the transaction.
Construction of apartments intended for sale before completion generally falls within the GST framework, while a sale after completion certificate or first occupation, whichever is earlier, is generally outside GST as a supply of goods or services.
For projects covered by the post-2019 real-estate regime, prescribed GST rates include 7.5% for non-affordable residential apartments and 1.5% for affordable residential apartments, with applicable conditions. Commercial apartments in an RREP can attract 7.5% under the specified entry.
The GST framework also contains specific conditions around input supplies, including the prescribed 80% procurement requirement from registered suppliers and reverse-charge provisions for specified purchases.
This makes project-level GST review an important part of real estate tax advisory services.
What Should Developers Know About Income Tax?
Real estate developers must carefully distinguish between capital assets, business inventory and development rights. Real estate tax advisory can help assess the tax treatment of land, construction expenditure, advances, borrowing costs and sale consideration based on the project structure and nature of the developer’s business.
The Income-tax Act, 2025 applies to Tax Year 2026–27 onwards, while the Income-tax Act, 1961 continues for earlier tax years and transitional matters. Developers should therefore review current projects under the law applicable to the relevant tax year rather than automatically carrying forward older interpretations.
How Important Is Project Accounting?
Project accounting is one of the most important areas for a developer.
Costs should be tracked project-wise and, where commercially relevant, allocated across:
Weak project accounting can distort project margins and create problems during tax assessments, audits, financing reviews and investor due diligence.
This is where real estate tax advisory services should work alongside accounting controls rather than functioning as a year-end tax exercise.
What About TDS on Property Transactions?
TDS obligations can arise at several stages of a real estate business. Real estate tax advisory can help developers review TDS on payments to contractors, professionals, brokers, employees, lenders and other vendors.
Property purchases can also trigger specific buyer-side TDS provisions. For example, Section 194-IA applies to certain purchases of immovable property, subject to applicable conditions.
Since TDS classification depends on the nature of the payment and recipient, developers should review relevant contracts and payment structures before making substantial payments.
What Tax Issues Arise in Joint Development Agreements?
JDAs can create complex tax questions for both the landowner and developer.
Key issues include:
The tax consequences can vary substantially depending on the contractual structure.
Therefore, real estate tax advisory services should ideally be involved before the JDA is executed, not after disputes arise.
How Can Developers Improve Tax Compliance?
A practical compliance framework should include:
Developers should also reconcile GST returns, books, invoices, bank statements and customer ledgers regularly rather than waiting for year-end.
How Can Real Estate Tax Advisory Support Growth?
Effective real estate tax advisory services should provide more than compliance.
A developer may need advice when:
An integrated real estate tax advisory approach can help management understand the tax cost of a commercial decision before committing to it.
What Common Mistakes Should Developers Avoid?
Common problems include:
These issues can increase tax exposure, interest, penalties and litigation risk.
Final Takeaway
Real estate taxation cannot be treated as a year-end compliance exercise. Developers need tax planning and accounting discipline throughout the project lifecycle.
From land acquisition and JDA structuring to GST, TDS, project accounting and final sale, real estate tax advisory can help developers make informed decisions while reducing avoidable compliance risks.
The best tax strategy is one considered before the transaction is structured, not after the tax liability has already arisen.
Frequently Asked Questions
Do real estate developers need specialised tax advisory?
Yes. Real estate involves project-specific GST, income tax, TDS, accounting and contractual issues. Real estate tax advisory can help developers evaluate these obligations together.
Is GST applicable on every property sale?
No. GST treatment depends on the nature and timing of the transaction. Construction intended for sale before completion can be taxable, whereas sale after completion certificate or first occupation, whichever is earlier, is generally outside GST.
Why is project-wise accounting important?
It provides visibility into actual project costs, margins, inventory and cash flows. It also supports accurate tax computation and audit documentation.
When should a developer seek tax advice?
Ideally, before acquiring land or signing a JDA. Early real estate tax advisory services can help identify tax consequences before a commercial structure becomes difficult or expensive to change.
Key areas covered:
- Tax structure should be considered from land acquisition through construction, sale and completion
- Under-construction sales generally attract GST; sales after completion certificate or first occupation generally do not
- Post-2019 GST rates include 7.5% for non-affordable and 1.5% for affordable residential apartments
- The Income-tax Act, 2025 applies from Tax Year 2026–27, with the 1961 Act continuing for earlier years
- Project-wise cost tracking supports margins, assessments, audits and investor due diligence
- TDS applies to contractor, professional, broker and lender payments, and to certain property purchases
- JDAs raise questions on development rights, consideration, timing, GST and valuation
- Regular reconciliation of GST returns, books, invoices and customer ledgers reduces exposure
Our insights
View more
12A & 80G Registration: What Is the Difference and Who Needs It?
6 min read | 3 Nov 2026
International Tax Planning for Indian Businesses: Key Areas to Consider
6 min read | 28 Oct 2026
GST, TDS & Income Tax: What Does a Small Business Need to File?
7 min read | 18 Aug 2026