ROC Annual Filing Checklist for Private Limited Companies
2 Oct 2026 · 5 min read
ROC annual filing is a yearly compliance requirement for private limited companies under the Companies Act, 2013. It involves filing the company's financial statements and annual return with the Registrar of Companies (ROC), along with maintaining the supporting records required for accurate reporting.
What Does ROC Annual Filing Include?
For a private limited company, the key annual filings generally include:
These filings are an important part of the company's overall corporate compliance services and should not be treated as simple form-filling exercises.
When Are ROC Annual Filings Due?
ROC annual filing deadlines are linked to the company's Annual General Meeting (AGM).
Companies should therefore plan their annual filing well before the deadline instead of treating ROC compliance as a last-minute exercise.
What Records Should Be Ready Before Filing?
A smooth ROC annual filing starts with proper record-keeping throughout the year. The company should have the following documents ready:
These records should be reviewed and kept ready to support the annual filings and ensure that the information reported to the ROC is accurate.
What Should Directors Check Before Filing?
Directors should review the information being reported before the forms are submitted.
This includes checking the company's financial information, shareholding, director details, meetings, registered office details and related-party transactions.
Any changes during the financial year should also be properly recorded and reflected in the applicable filings.
What Happens If ROC Filing Is Delayed?
Delayed ROC annual filing can result in additional fees and penalties under the Companies Act, 2013.
For annual return defaults under Section 92, the penalty can be Rs 10,000 initially, plus Rs 100 per day for continuing failure, subject to a maximum of Rs 2 lakh for the company and Rs 50,000 for the officer in default.
For financial statement filing defaults under Section 137, the penalty can similarly be Rs 10,000 initially, plus Rs 100 per day for continuing failure, subject to a maximum of Rs 2 lakh for the company and Rs 50,000 for the officer in default.
Additional fees may also apply to delayed filings under the applicable provisions.
A prolonged compliance default can create further consequences. For example, failure to file financial statements or annual returns for three continuous financial years can trigger director disqualification provisions under Section 164(2).
Other Compliance
ROC annual filing is only one part of a company's overall compliance framework. Depending on the company's activities and circumstances, other requirements may include:
These requirements should be tracked separately so that an annual filing does not become the only focus of the company's compliance process.
How Can Companies Make ROC Filing Easier?
Companies can make ROC annual filing more efficient by maintaining statutory registers throughout the year, recording corporate changes on time and keeping financial and corporate records reconciled.
Professional corporate compliance services can help coordinate accounting, audit, Board documentation and MCA filings so that the information remains consistent throughout the year.
For businesses completing the incorporation of private limited company, setting up a proper compliance process from the beginning can prevent small record-keeping issues from becoming bigger problems later.
Final Takeaway
ROC annual filing is not just about submitting forms before a deadline. It is about ensuring that the company's financial and corporate information is accurate, updated and properly documented.
A practical process is: Finalise and audit the financial statements, hold AGM, file AOC-4, file MGT-7/MGT-7A, then preserve records.
When these steps are handled systematically, companies can reduce compliance gaps and avoid unnecessary delays and penalties.
Frequently Asked Questions
What are the main ROC annual filings for a private limited company?
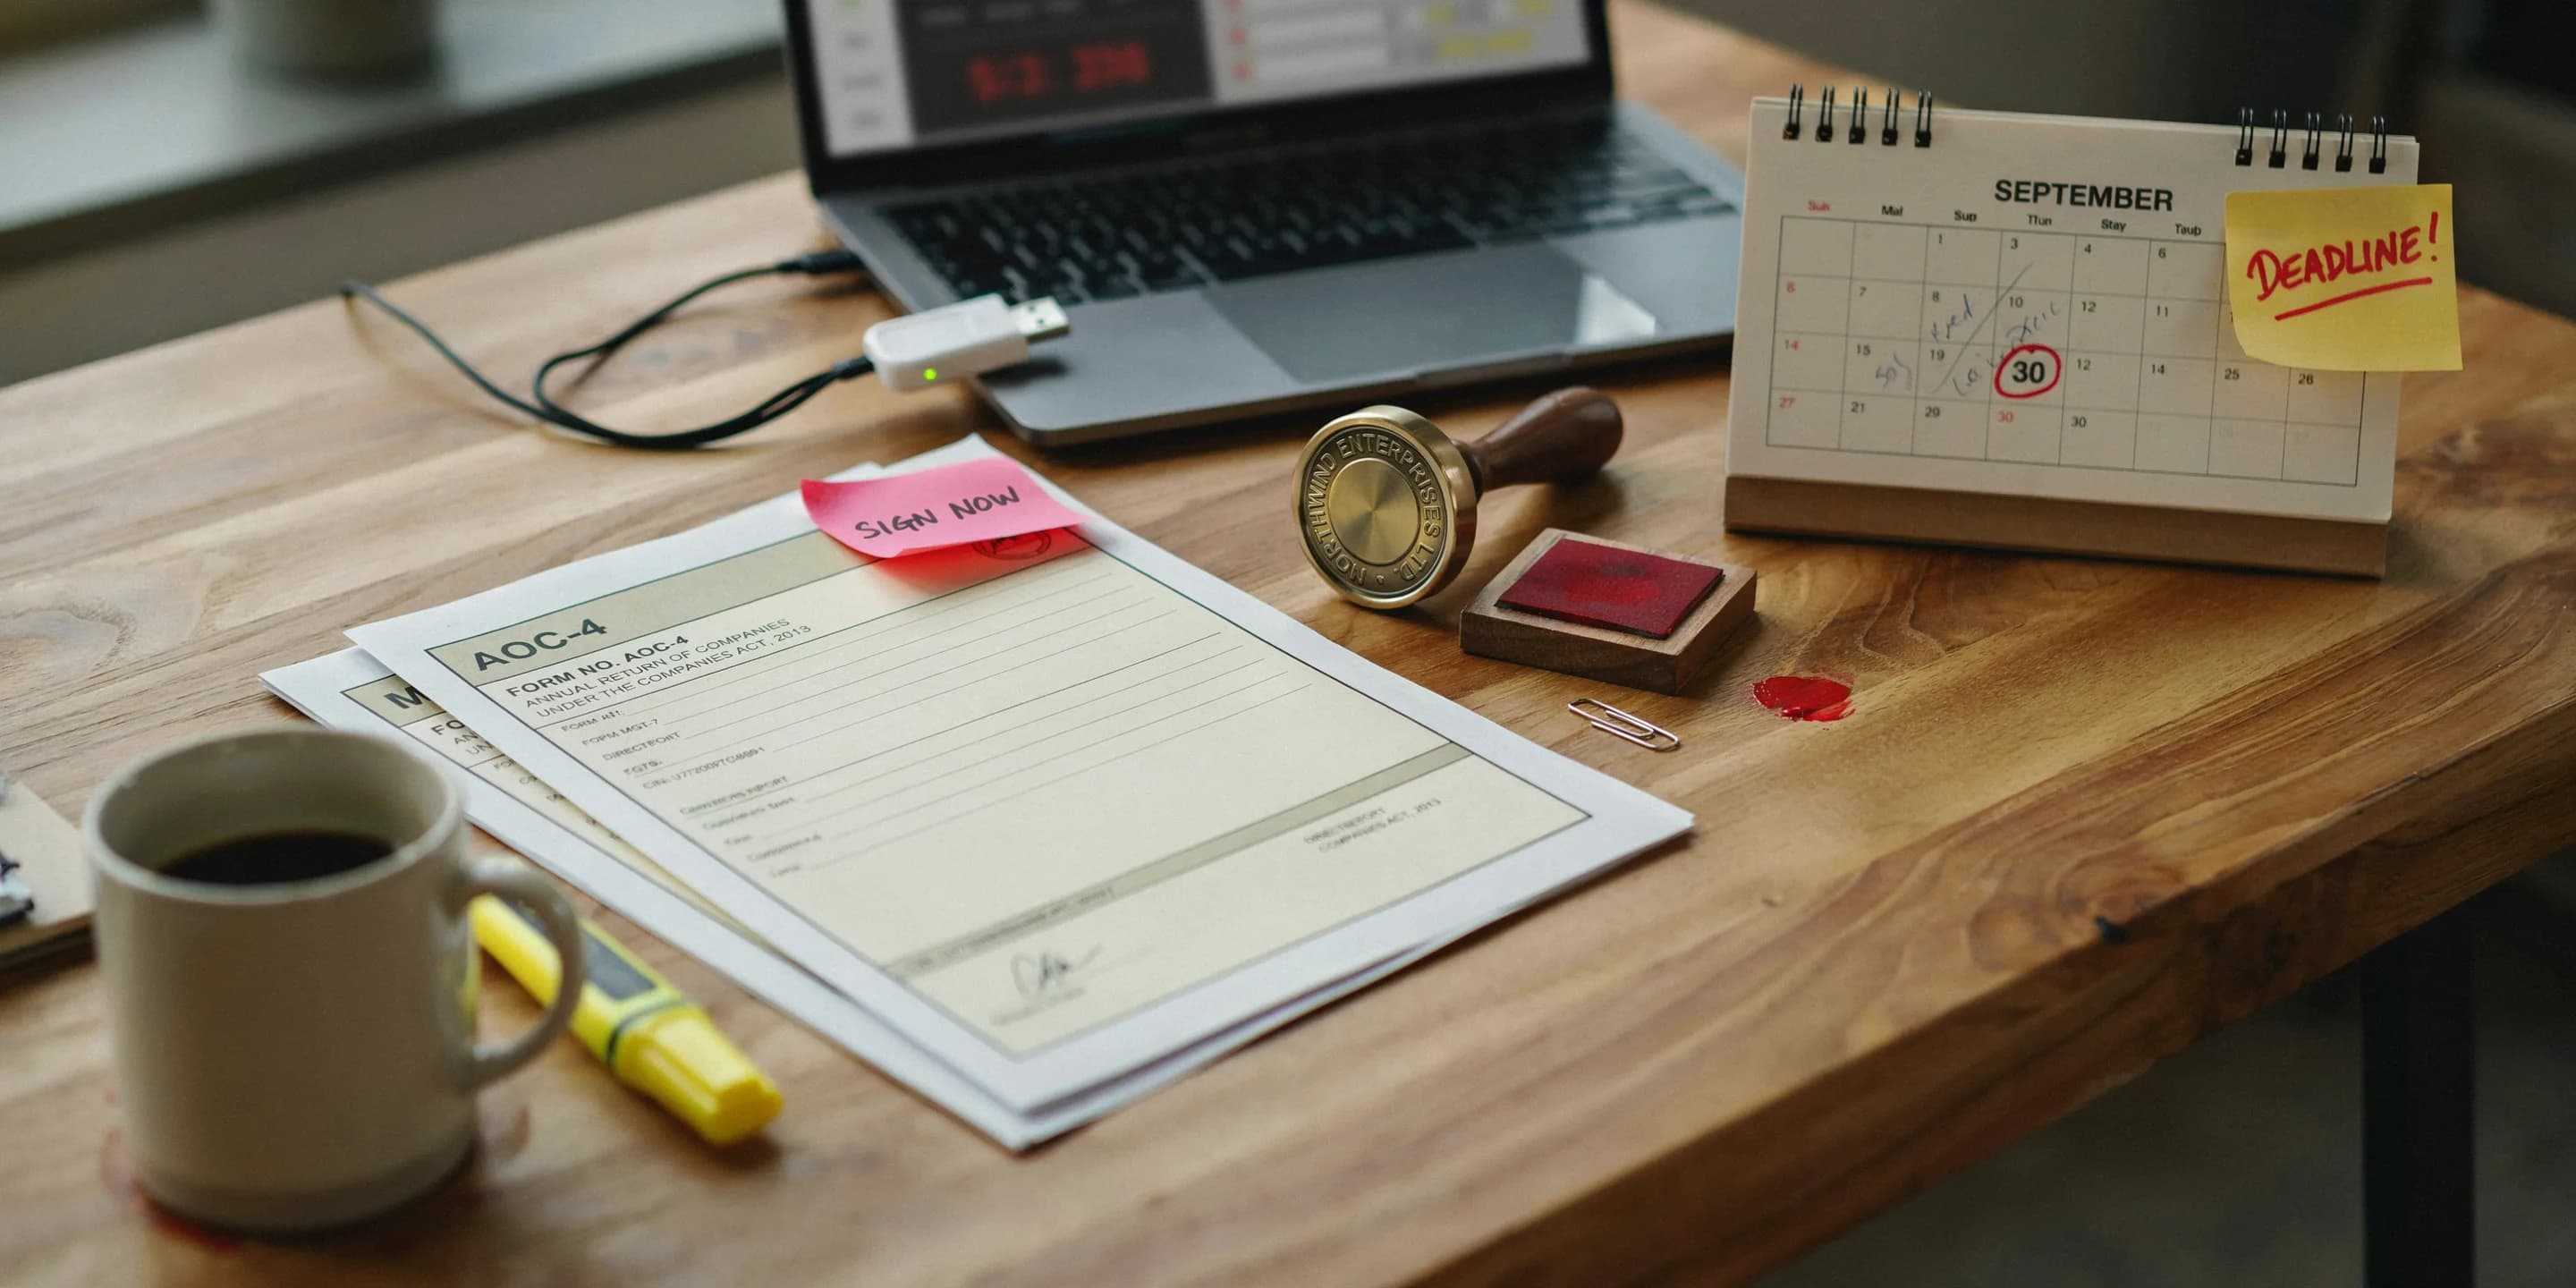
The main filings generally include AOC-4 for financial statements and MGT-7 or MGT-7A for the annual return, depending on the company's category.
When is AOC-4 due?
AOC-4 is generally due within 30 days of the AGM.
When is the annual return due?
MGT-7 or MGT-7A is generally due within 60 days of the AGM.
Does a company with no business still need to file its annual return?
Yes. A company generally continues to have annual filing obligations even when it has little or no business activity, subject to the applicable legal requirements.
Key areas covered:
- AOC-4 (financial statements) is due within 30 days of the AGM
- MGT-7/MGT-7A (annual return) is due within 60 days of the AGM
- Late filing under Section 92 or 137 can attract penalties of Rs 10,000 plus Rs 100 per day up to Rs 2 lakh
- Three consecutive years of non-filing can trigger director disqualification under Section 164(2)
- ROC filing is only one part of a company's compliance framework - other filings like Director KYC and MSME reporting must also be tracked
- Setting up a compliance process from incorporation prevents record-keeping issues from escalating later